September 25, 2026
Everyone Sold P&G to Buy Nvidia and Now BofA Is Flagging the Reversal
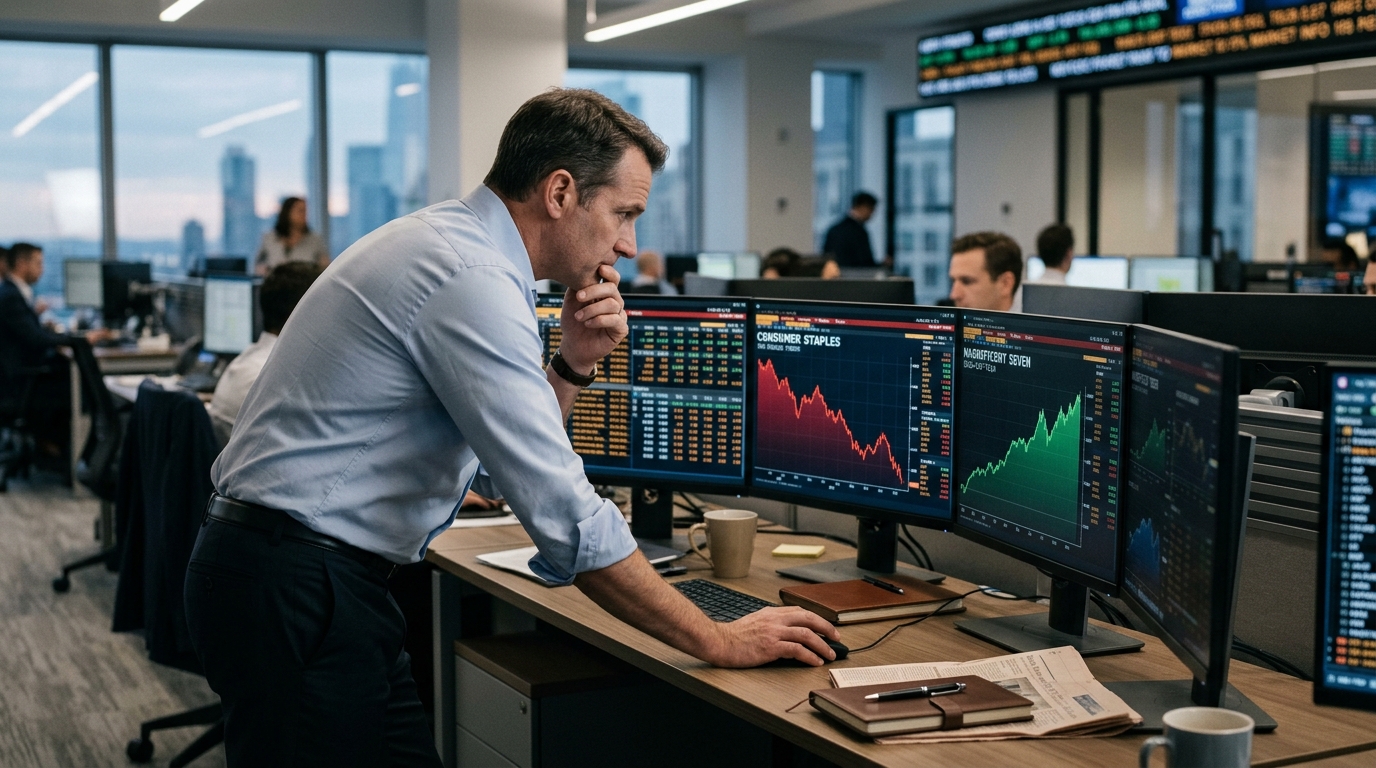
Consumer staples hit a 22-year underweight in September. The funding source is bond books, not defensives. That gap closes eventually.
Here is what the September BofA Global Fund Manager Survey actually tells you, if you read it the right way: professional investors are not rotating into safety. They are funding a bet on the Magnificent Seven out of their bond books, and they are leaving consumer staples behind at a level of contempt not seen since January 2004.
What is “The Presidio Initiative”?
A single $20 million check delivered to a former military base may have launched the biggest megaproject in American history.
That is the real story inside a survey most commentators have reduced to a headline about cash levels.
What the Survey Says
In BofA’s September Global Fund Manager Survey, consumer staples fell to a net 33% underweight, the most bearish positioning since January 2004. To put that in context, the underweight moved from a net 19% just a month earlier, a 14-point swing in a single survey. September also saw rotation into healthcare, industrials, and banks, with banks and insurance at their most overweight positioning since November 2025. Real estate investment trusts also moved more underweight alongside staples.
Cash holdings rose to 3.9% of assets from 3.5% in August, which BofA described as the largest monthly increase since March 2026. That sounds cautious. It is not the whole picture. BofA’s own survey summary also noted that conviction in strong growth and AI capital expenditure remained firm, even as concerns over disorderly bond-yield moves were rising.
The 4 dates that blow up options trades
Quick one.
You can grab my new Options Landmine Calendar free today – normally $29.97.
It covers the 4 recurring events that blow up options trades – scheduled disasters that are published in advance, in plain sight, and that beginners walk into constantly.
You’ll learn what each one is, why it detonates options positions, where to find each date in 30 seconds for free, and the 5-Minute Check that sweeps all four before any trade.
Download your free copy right here.
Heads up: That link expires soon.
The Bond Book Is the Funding Source
What makes this rotation genuinely unusual is where the money for the Magnificent Seven is coming from. It is not flowing out of defensives and into growth in the traditional sense. Fund managers are now net 48% underweight bonds, the biggest underweight since May 2022 and the 17th straight month of underweight positioning. Bonds are the source of funds, not staples.
Meanwhile, the mega-cap complex has been back in focus as September progressed. The Roundhill Magnificent Seven ETF (MAGS) was up about 5% month-to-date around mid-September, outpacing the broader market over the same stretch. Meta Platforms has been a standout in that move after launching its consumer AI agent, Muse, earlier this month.
The yield backdrop makes this all the more striking. The 10-year Treasury yield jumped to about 5.11% on Wednesday, Sept. 23, 2026, around a 15-basis-point move on the day, pushing to its highest levels since 2007. There is a clear reason managers are drawn to the Magnificent Seven here: the group’s scale, cash flow, and balance sheets make it a perceived safe haven in a rising-rate environment that punishes both stocks and bonds. Some multi-asset managers have framed the trade-off bluntly, arguing that large-cap platform balance sheets can look more attractive than adding duration at these yield levels.
Nuclear Energy’s Comeback Could Spark Before 2026
Global energy demand is surging and one overlooked power source is quietly returning to the spotlight. New policy support and supply constraints are setting the stage for a surprising shift in the energy markets.
What Investors Are Missing
The conventional logic in a rising-rate, defensive-rotation environment says money should be moving into staples. Procter & Gamble, General Mills, Costco, the classic “sleep well at night” holdings. Instead, those names are the most unloved they have been in more than two decades. BofA’s own contrarian trade framework has flagged going long consumer staples as a recommended contrarian position, alongside UK equities and small caps.
That is the hidden tension. When a crowded consensus finally cracks, the reversal tends to be fast. Managers funding MAGS strength out of bond books with the 10-year around 5% have less room for error than the positioning implies.
Stocks to Watch
- MAGS: The clearest expression of the mega-cap trade. Up roughly 5% month-to-date at points in September, even as Treasury yields pushed back toward 5%.
- XLP: The consumer staples ETF sitting at a 22-year positioning low in the survey. XLP is the default parking spot for defensive exposure, and it has done its job in 2026, up about 10.75% year to date as of Aug. 31, 2026, yet institutional money is walking away regardless.
- Procter & Gamble (PG): Among XLP’s largest holdings. The extreme underweight means any shift in sentiment hits PG first and hardest on the upside.
- General Mills (GIS): Packaged food is the unloved corner of an already unloved sector. General Mills shares were down roughly a third over the prior 12 months in early 2026, making it a notable detractor within staples.
- XLV and XLF: The beneficiaries of where the rotation actually went. Healthcare and banks are drawing fresh institutional interest precisely as staples are being abandoned.