One Asset Gained 2,300%
The Last Time This Setup Happened
Here’s What It Was
Dear Reader,
From 1970 to 1980, one specific asset gained more than 2,300%.
That’s not a typo. A $10,000 investment became $230,000 in a decade.
And here’s why we’re bringing it up right now.
The exact same conditions that produced that gain in the 1970s are forming again today.
Stagflation. The toxic combination of high inflation AND a stalled economy. The 1970s version trapped the U.S. economy in a vise for nearly a decade. Stocks went sideways for 10 years. Bonds got crushed. Cash lost half its value.
Now look at where we are:
Inflation expectations spiked to 4.8%. JP Morgan and Moody’s are warning of recession by 2026. Oil is surging on Middle East tensions. And the Fed is trapped – cut rates and inflation worsens, hike rates and recession arrives faster.
The setup is identical.
Now we know what you’re thinking. “That was 50 years ago. It can’t happen again.”
The smartest money in the world disagrees.
Central banks are loading up on the same asset that gained 2,300% in the 1970s – at the fastest pace in 50 years. JP Morgan is forecasting it could hit $8,000 before this cycle ends.
You’re going to make a decision today whether you realize it or not.
Position before stagflation locks in. Or watch from the sidelines while the same trade plays out again.
Because once the trap closes, getting out gets expensive.
TSMC’s Record October Puts the AI Debate to a Vote
The investment committee argument over artificial-intelligence spending has been raging for four months. On Monday morning, the foundry at the center of that argument handed the room its first hard, unfiltered data.
The Big Question
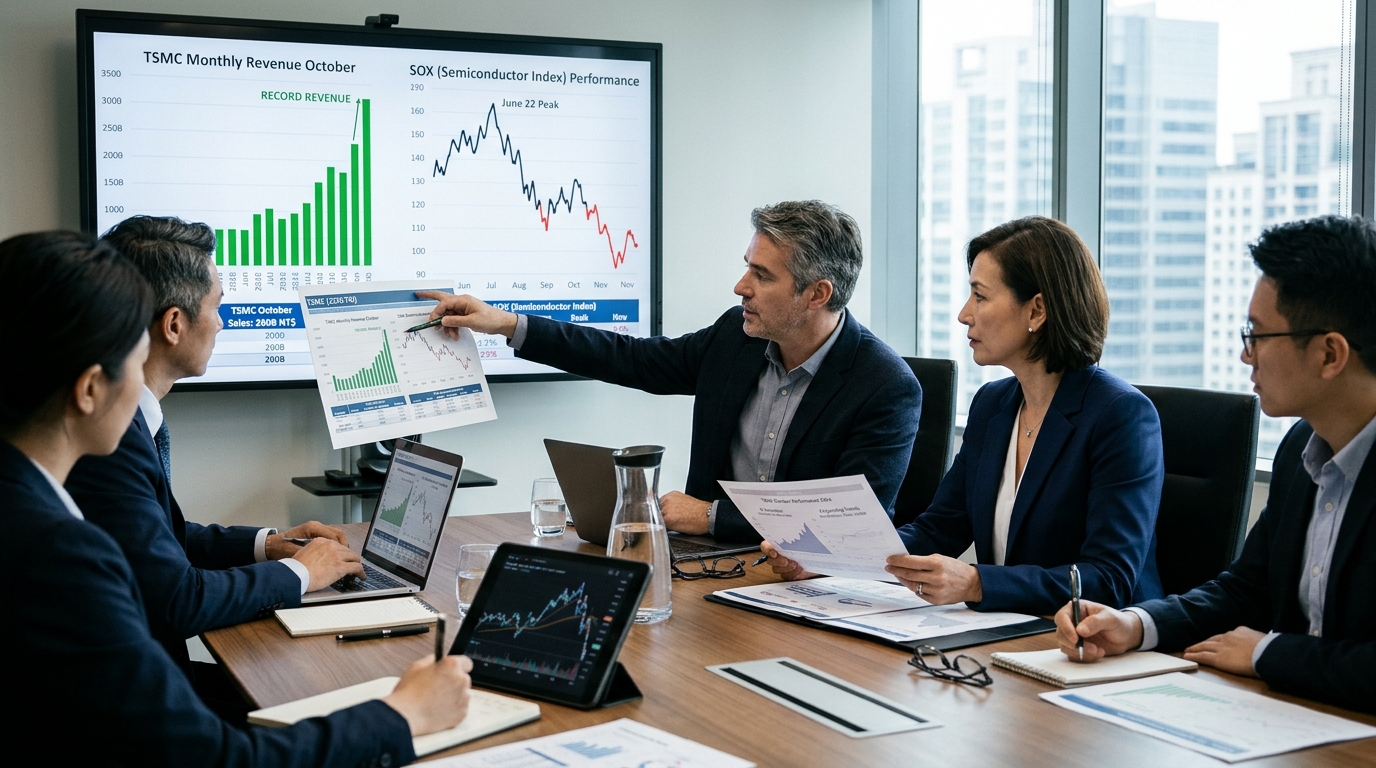
Is AI infrastructure spending peaking, or is the semiconductor selloff a valuation correction unconnected to actual demand? The SOX index is down about 37% from its June 22 high, per a Bank of America note circulated this week. The bear case says that gap reflects a genuine growth scare. The bull case says the market sold the wrong asset. TSMC’s October numbers are the most direct test either side has had.
Why Wall Street Cares
TSMC reported October revenue of NT$586.89 billion, up 59.7% from a year earlier and up 14.7% from the previous month. That is the best month TSMC has ever recorded, clearing August’s NT$514.81 billion, which had been the 2026 high until now. For the first ten months of 2026, cumulative revenue reached NT$4.48561 trillion, up 43.3% compared to the same period in 2025.
October’s record sales exceeded the average monthly run-rate of about NT$575.6 billion needed to reach the high end of management’s fourth-quarter revenue target range that the company discussed in October, putting the foundry on pace for another record quarterly performance.
The Bull Case
TSMC does not sell fear or forward guidance. It sells wafers. A 59.7% year-on-year revenue surge, delivered at the foundry’s highest monthly output ever, is a physical measure of chips leaving fabs and entering data centers. On its 2026 earnings calls, management has said it raised its full-year 2026 capital budget to US$60 billion to US$64 billion to support continued strong multi-year customer demand, and that spending across 2026 to 2028 will be significantly higher than in the preceding three years. At the node level, management has also described continued strength at the leading edge, with N2 ramping and additional N3 capacity being added.
The Bear Case
The selloff was not random. After the U.S. midterm results, Dan Ives said he now expects Big Tech capital-expenditure growth to peak in 2027, pulled forward from his prior 2028 to 2029 view, and warned that roughly 10% to 20% of 800 to 1,000 planned U.S. AI data centers could be scrapped or face lengthy delays. The concern is that TSMC’s October strength reflects orders placed months ago, not today’s investment climate. Bookings from hyperscalers who are now reconsidering permit timelines would not yet show up in revenue.
The same tension between strong foundry data and falling stock prices is playing out one layer down the stack. Memory stocks dropped more than 25% while DRAM revenue approached five times its year-ago level, a dislocation that raises the same sequencing question TSMC’s October number cannot yet answer.
The Evidence
Chip stocks now trade at a 22% discount to the S&P 500, according to a Bank of America note circulated this week, after the SOX fell about 37% from its June peak. In that note, the SOX was described as trading at 13.7 times forward earnings versus 17.7 times for the S&P 500; at the height of the AI rally, chip stocks traded at a premium to the market. Meanwhile, on its 2026 earnings calls, TSMC management has reaffirmed the 2026 capital budget of US$60 billion to US$64 billion and said spending across 2026 to 2028 will be significantly higher than in the preceding three years.
The Mavens’ View
Some strategists have framed the semiconductor decline as a recalibration of expectations rather than a fundamental break in the AI investment story. That framing is doing a lot of work. The honest version is that two things are simultaneously true: AI chip demand, as measured at the foundry, has not broken. And the political and financing conditions that determine how long demand stays elevated have changed in ways TSMC’s October report cannot yet capture.
What Investors Are Missing
The debate has been framed as AI spending versus chip valuations. The more productive question is sequencing. A 2027 peak in capex growth carries a subtle message: peak growth does not mean spending stops; it means the rate of increase starts to flatten. TSMC’s October number confirms the volume is there today. What it cannot confirm is whether October 2027 will look the same. The companies most exposed to that sequencing risk are not TSMC, whose annual report says it manufactured products for 534 customers, but the pure-play AI hardware names whose valuations assumed an indefinitely steepening curve.
Stocks to Watch
- TSMC (TSM / 2330.TW): The October data makes the Q4 guidance look conservative. The stock remains the least binary way to own AI silicon demand across any political outcome.
- Nvidia (NVDA): TSMC leadership has repeatedly emphasized that AI-related demand remains very strong relative to supply. Nvidia is the primary beneficiary if that gap persists, but it trades on 2027 earnings that now carry political timing risk.
- AMD (AMD): October’s numbers are unambiguously positive for its production schedule.
- ASML (ASML): ASML reported €11.7 billion of total net sales in the third quarter of 2026. As the sole supplier of extreme ultraviolet lithography tools, any capex acceleration at TSMC flows directly to its order book, with a multi-year lag that insulates it from near-term political noise.