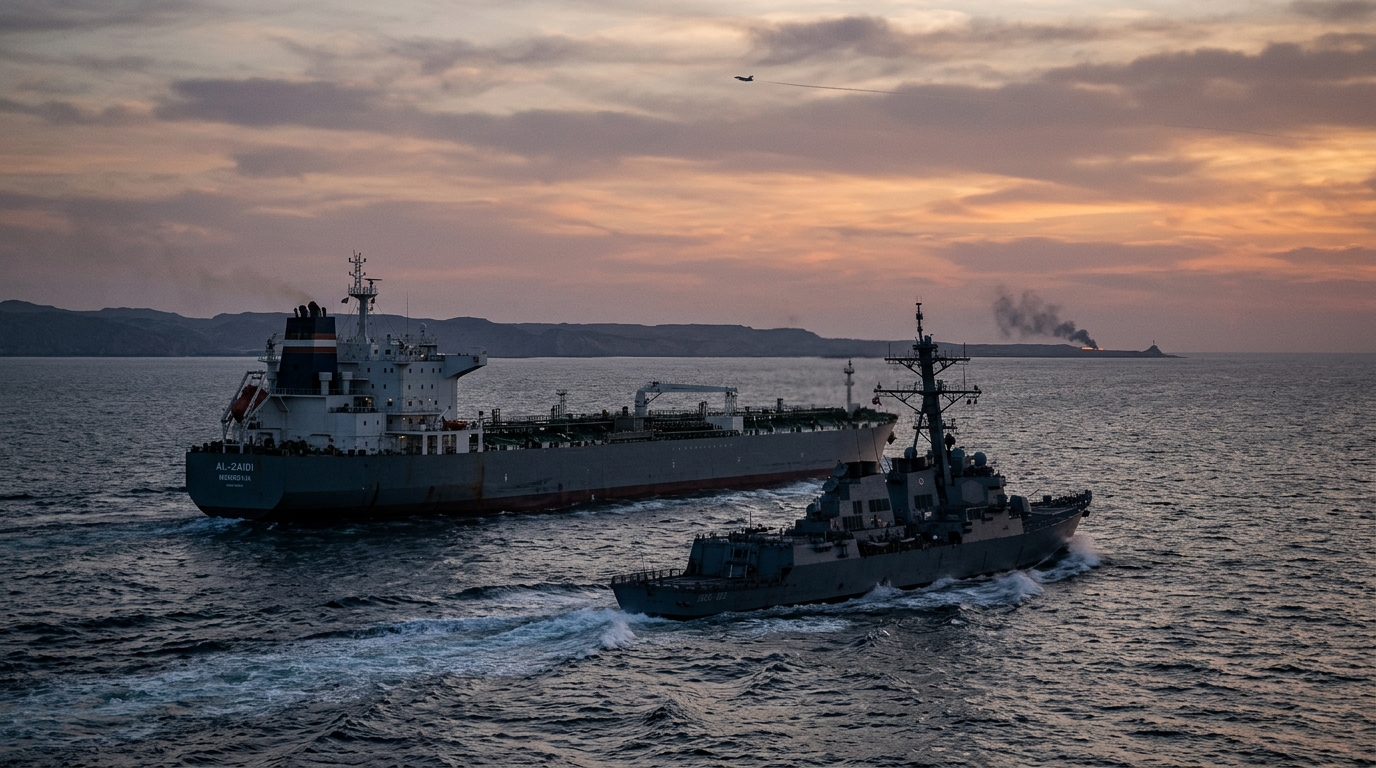
Two events hit the wire over the weekend that the Friday close could not price in. On Saturday, a U.S. military aircraft fired precision munitions at the stern of the M/V Huda, a St. Kitts-flagged cargo ship in the Gulf of Oman, after the crew attempted to break the U.S. naval blockade on Iran and ignored repeated warnings. The UAE National Guard subsequently rescued 22 crew members after a fire broke out aboard a cargo ship in the Gulf of Oman. Then on Sunday, CENTCOM announced it had established Task Force Iron Gate to disrupt Iran’s land-based supply routes, expanding the months-long naval blockade in and around the Strait of Hormuz.
The two moves together close a loop. The new team will coordinate with other U.S. government agencies on preventing the movement of advanced weapons systems, dual-use technologies, sanctioned materials, and illegal revenue streams across Iran’s land borders and the Caspian Sea. On the other side, Iran’s Revolutionary Guard lifted its self-proclaimed limit of 2,000 kilometers on the range of its ballistic missiles, suggesting the country may seek to develop missiles capable of reaching more distant targets amid fears of renewed all-out war. Neither side is signaling retreat.
Market Snapshot
Brent was at $97.76 on November 6, the last trading session before the weekend escalation. WTI stood at $90.83 on the same day. Both benchmarks closed before CENTCOM struck the Huda and before Task Force Iron Gate was announced, leaving this morning’s open to absorb the full weekend development. Key technical levels for WTI vary by model and will reset with the open.
The Strait of Hormuz is effectively closed to commercial shipping as of this morning, with one vessel transiting on November 1 against a normal daily count of roughly 85. That is not a new number, but the weekend events confirm enforcement risk is still elevated.
Stocks in Focus
Tanker names are the most direct expression of this trade. Baltic Exchange-linked reporting showed VLCC earnings on Middle East Gulf to China benchmarks surged above $1 million per day in October, far above early-year levels. Rates pulled back this past week from record highs, with the Gulf of Oman-to-China VLCC benchmark around WS 776 on the Worldscale basis. Saturday’s strike on the Huda adds fresh risk premium. Frontline (FRO), Teekay Tankers, International Seaways (INSW), and Euronav are the names most directly sensitive to rate moves in this region.
Several large crude-tanker owners have posted materially stronger results during the disruption, but the question for Monday is whether the weekend strike reignites the rate spike that briefly cooled late last week, or whether the market treats the Huda incident as routine enforcement rather than a new threshold crossed. Task Force Iron Gate’s land-route mandate does not directly move tanker rates, but it signals that Washington is widening the pressure campaign, reducing the probability of a near-term settlement that would reopen Hormuz traffic and normalize freight costs.
Sector Watch
Energy is the dominant sector today. U.S. officials have publicly argued the blockade has denied Iran tens of billions of dollars in crude-export revenue. Independent tracking and consultancy estimates around Iranian export leakage vary, but the core point for traders is unchanged: the Strait disruption and enforcement posture keep Middle East supply risk embedded in the tape.
Risk Radar
- Iran missile escalation. Tehran removing its self-imposed 2,000-km missile range ceiling removes a constraint that had bounded the conflict’s geographic scope. Traders in energy and regional equities should treat this as an ongoing tail risk rather than resolved noise.
- Tanker rate whipsaw. Rates fell last week on diplomatic speculation and softening demand. A second strike, or an Iranian response to the Huda incident, could reverse that move sharply. Positioning in tanker names ahead of that volatility carries gap risk.
- Cargo ship flag-state complications. UK Maritime Trade Operations reported an incident involving a commercial vessel in the Gulf of Oman but did not immediately confirm it was the same ship targeted by U.S. forces, illustrating how confused the operational picture remains for vessels transiting the area.
The Cheat Sheet
Top theme: The Iran blockade shifted from interdiction to kinetic enforcement over the weekend. The market has not priced that yet.
Stock to watch: Frontline (FRO). Highest direct exposure to VLCC rate moves, with a large fleet positioned across the conflict zone’s key routes.
Sector to watch: Energy. Crude supply constraints from the blockade are real, and Task Force Iron Gate extends that pressure to overland routes.
Biggest risk: Iran’s missile range announcement. If Tehran translates that signal into action against regional infrastructure, the conflict scope changes materially for energy markets.
One thing to remember: Brent and WTI closed Friday before either the Huda strike or Task Force Iron Gate was public. The open is the market’s first chance to respond to both. Watch the first 30 minutes in crude futures and tanker names before drawing any directional conclusions.