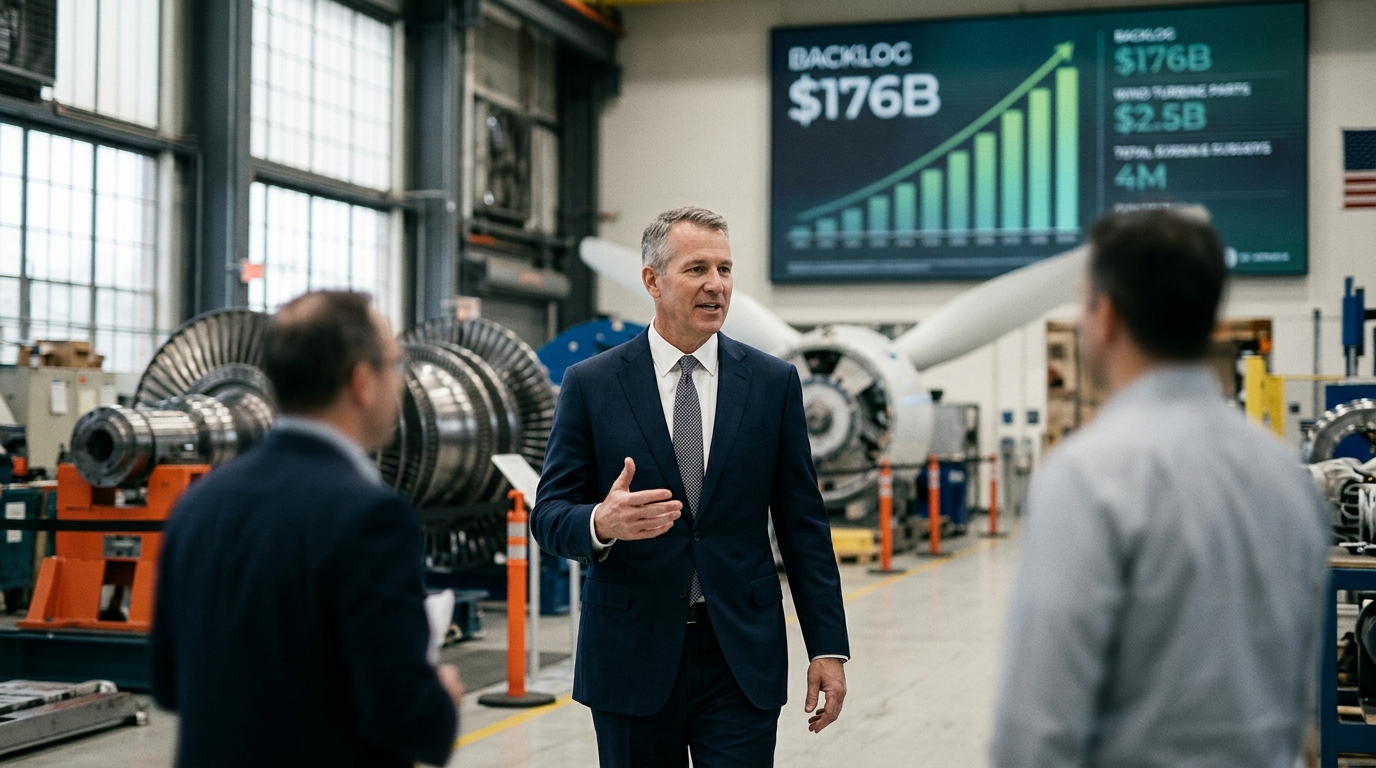
GE Vernova’s stock has spent the past month giving back gains. The company has spent the same period adding to one of the largest industrial order books in history. That gap between price direction and business momentum is the investment question worth answering right now.
Why This Stock Now
GE Vernova CEO Scott Strazik said at Morgan Stanley’s Laguna Conference on September 16, 2026, that the company expects backlog to surpass $200 billion in early 2027. GEV is up 44% year to date and roughly 54% over the past year, despite a pullback over the past month. That pullback, combined with a structural order book now approaching $200 billion, is the starting point for the argument.
The Business
GE Vernova makes gas turbines, grid electrification equipment, and wind turbines. The power and electrification divisions are the ones that matter to investors right now, because hyperscalers need enormous amounts of reliable electricity to run AI data centers, and they are signing contracts for generation and grid equipment to get it.
Hyperscalers such as Amazon, Google, Microsoft, and Oracle are competing for gas turbine capacity to power data centers, with GE Vernova positioned as a key supplier. That strategic position was reflected in second-quarter 2026 financial results, which showed revenue increasing 22% year over year to $11.1 billion, beating Wall Street’s forecasts of about $10.8 billion.
The order pace is accelerating. GE Vernova booked 113 gas turbine orders in the second quarter, up from 81 a year earlier. Orders for its largest heavy-duty gas turbines rose from 20 to 52 over that period.
Why Wall Street Is Paying Attention
GE Vernova said it expects to have at least 125 gigawatts of gas power equipment backlog and slot reservation agreements under contract by year-end 2026, and said it remains on track to reach 20 GW of annual gas turbine output in the third quarter of 2026, ramping to 24 GW in 2028 and targeting 30 GW by 2030.
Customers are putting cash down on delivery slots years in advance. That is contracted revenue years out, not speculative pipeline. GE Vernova increased its 2026 revenue forecast to between $45.5 billion and $46.5 billion and raised its free cash flow outlook to $11.5 billion to $12.5 billion. The company generated $5.1 billion in free cash flow in the second quarter, more than it produced during all of 2025.
Institutional conviction has held through the recent weakness. Insider Monkey’s first-quarter 2026 database shows 118 prominent hedge funds with long positions in GE Vernova, up from 115 in the previous quarter. After the CEO’s appearance at the Morgan Stanley conference, Bernstein reaffirmed an Outperform rating and a $1,298 price target.
What Could Go Wrong
The wind division is a real drag. Wind segment revenue was $3.459 billion for the first six months of 2026, down 16% from the prior year. Wind orders fell roughly 40% from a year earlier, and the segment’s EBITDA loss widened by $110 million to $275 million in the second quarter. Every dollar lost there reduces the earnings impact of the gas turbine boom.
The company posted adjusted EPS of $2.47 in Q2, about $0.57 below the $3.04 estimate. Management warned that anticipated global tariff changes could add $100 million to $200 million in cost headwinds in 2026. Conservative investors may feel uncomfortable with a valuation that still looks demanding for an industrial company working through execution challenges in wind and facing tariff uncertainty on imported components.
The Bottom Line
GE Vernova is building gas turbines as fast as it physically can, has a $176 billion backlog heading toward $200 billion, generates more free cash flow in a single quarter than it did in all of 2025, and trades about 20% off its high after a recent pullback. That disconnect between the order book and the stock price is the opportunity. The wind division and tariff exposure are the risks that keep the valuation where it is. For investors willing to hold through the noise, the structural demand case remains intact.