October 19, 2026
Bonus Content: The CSI 300 Has a Buyer. That Is Not the Same as a Bottom.
Dear Reader,
When it comes to picking winners in all market conditions…
Wall Street insider Jason Bonder is the man you should listen to.
Since 2014, his research flagged more than 70 stocks that went on to gain 500% or more.
29 of them topped 1,000%.
And when we back tested his system all the way to 1990, the numbers got even bigger…
More than 350 stocks gained over 1,000%…
38 topped 5,000%…
And 15 delivered 10,000% or more.
Now, Jason’s system just flagged his #1 pick for 2026 and beyond.
Click here to get the name and ticker symbol – for free.
Regards,
Lindsey Hough
Managing Director, Brownstone Research
The CSI 300 Has a Buyer. That Is Not the Same as a Bottom.
The question landing on investment committee agendas this Monday morning is not whether Beijing is buying Chinese equities. The flow data makes that case convincingly. The question is what that buying actually means for risk-adjusted returns in a market that has just posted a losing streak with no modern precedent.
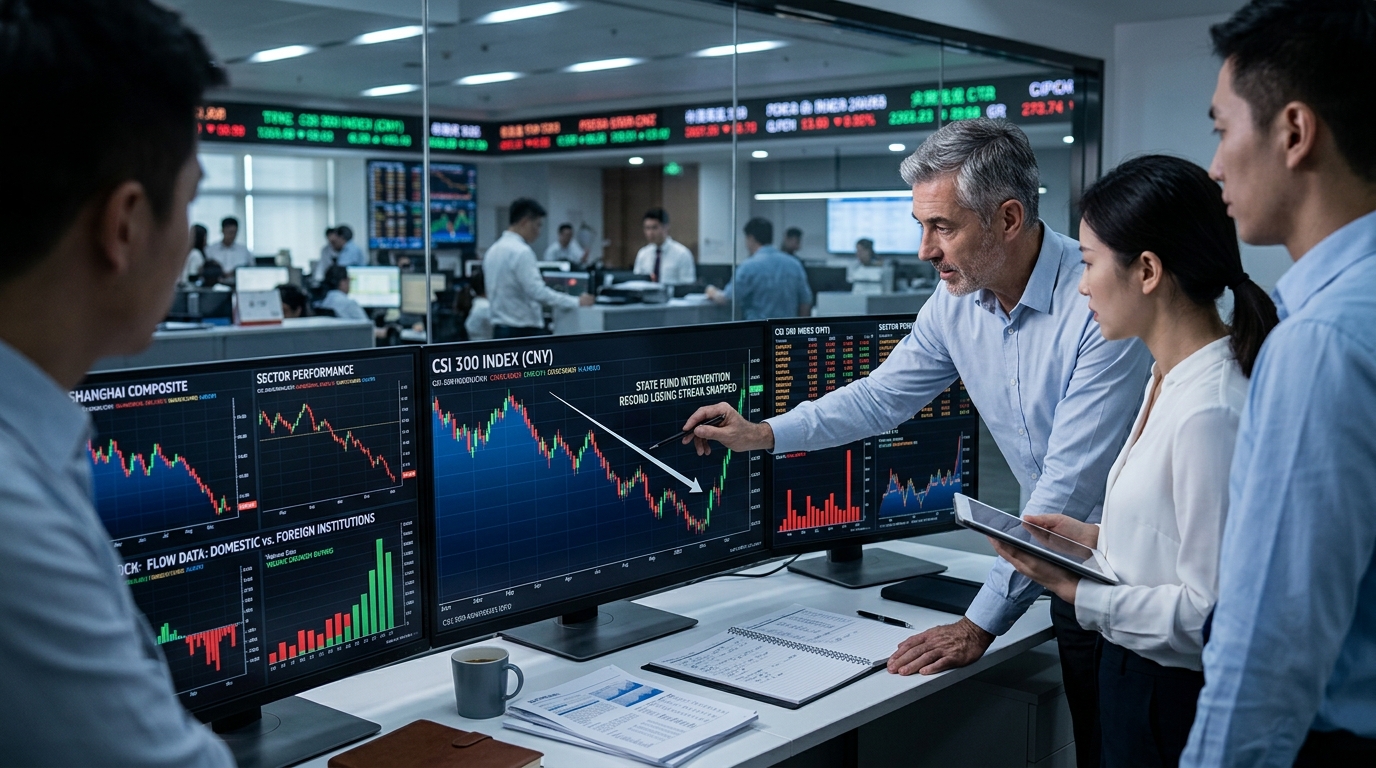
Signs are emerging that a record 10-week losing streak for China’s CSI 300 prompted state-backed funds to step up their presence, with inflows into a basket of ETFs favored by the so-called National Team surging last week to the highest since July. There is no official confirmation that state funds are behind the buying, but the size and timing of the flows have many market participants convinced that Beijing is looking to support the market.
The intervention did not materialize in isolation. China moved to stabilize its equity market by urging companies and state funds to buy shares while guiding some investors to curb selling, with financial regulators holding a meeting on October 15, 2026, to discuss stabilization measures. Major insurers received informal window guidance to report their equity holdings, avoid locking in losses on positions trading below cost, and align their investment decisions with broader economic objectives. The coordinated character of these moves matters: this is not opportunistic buying. It is administered price support.
What the Bull Case Looks Like
State buying and selling curbs typically put a floor under Chinese equities in the short term, so near-term downside in mainland indices may be more limited than global tech peers suggest. After ten consecutive weeks of declines, valuations have compressed sharply. The measures followed a slump that sent the CSI 300 to its lowest since August 2025. FXI, the iShares China Large-Cap ETF, is down roughly 10% year to date; KWEB, which tracks Chinese internet names through positions in Tencent, Alibaba, and PDD Holdings, has fallen around 28%. At those levels, any stabilization in selling pressure looks mathematically meaningful.
The bull argument has one more leg: the National Team concentrates its purchases in broad CSI 300 ETFs. That mechanical buying compresses the index’s volatility independently of fundamentals, which can be enough to attract momentum-sensitive investors and stop a self-reinforcing liquidation cycle.
The Bear Case Is Structural, Not Tactical
Here is where the professional debate gets sharper. That support is administrative rather than fundamental, and rallies built on directed buying have often faded once the intervention eases. This pattern has repeated itself. In 2015, with a vastly more favorable economic backdrop, the effect of National Team buying was debatable. It took months for markets to find a bottom and more than five years for the CSI 300 to regain its peak.
“China’s national team is offering market protection, not macro repair,” says Geoffrey Yu, strategist at BNY Mellon. “State-backed equity purchases can stabilize benchmarks and reduce downside pressure, but they don’t solve weak domestic demand or the property drag. Beijing can protect prices, but confidence still requires a stronger growth impulse.”
The sell-off has been concentrated in technology and AI-related shares, which had powered much of the market’s earlier gains. Chinese stocks have also been caught in a broader global technology rout, with South Korea’s Kospi plunging more than 7% and Japan’s Nikkei 225 falling almost 5% as investors reassessed AI valuations. Domestic state buying cannot insulate Chinese tech from a global reset in AI multiples.
The pressure on Chinese tech names is not purely a sentiment story. Baidu’s GPU cloud revenue surged while its core ad engine kept shrinking, showing how uneven the recovery inside Chinese internet actually is.
What Investors Are Missing
The overlooked consequence here is the distortion the National Team creates within the index. “The rescue is unbalanced. They mainly save the central state-owned enterprises and the blue-chip CSI 300 stocks,” according to Pang Xichun, research director at Nanjing RiskHunt Investment Management. That means FXI, which tilts heavily toward financials and state-linked large-caps, absorbs a disproportionate share of the bid. KWEB, concentrated in consumer internet names that trade in Hong Kong and New York, receives far less direct support and remains fully exposed to the global AI sentiment reset.
Historical data on National Team announcements shows that following their buying is profitable over a one-year horizon, but over one, three, and six months there has typically been more pain than gain. That is the asymmetry fund managers need to price correctly before treating a state buyer as a buy signal.
Stocks to Watch
CSI 300 broad ETFs (onshore): The direct beneficiary of National Team flows. State buying flows almost exclusively into these vehicles, providing mechanical price support regardless of earnings momentum.
FXI: FXI offers broader, less volatile exposure to China’s overall economy and is down about 10% year to date. Its heavy weighting toward financials means it benefits more than most from administered stability, but its P/E of around 11x leaves room for mean reversion if the intervention holds.
KWEB: A pure-play on Chinese tech and internet and down 28% year to date, KWEB is more likely to gain from consumer spending and AI growth than from intervention mechanics. State support does not reach it directly. Owning it here is a macro bet on Chinese consumption recovery, not a play on Beijing’s buying program.