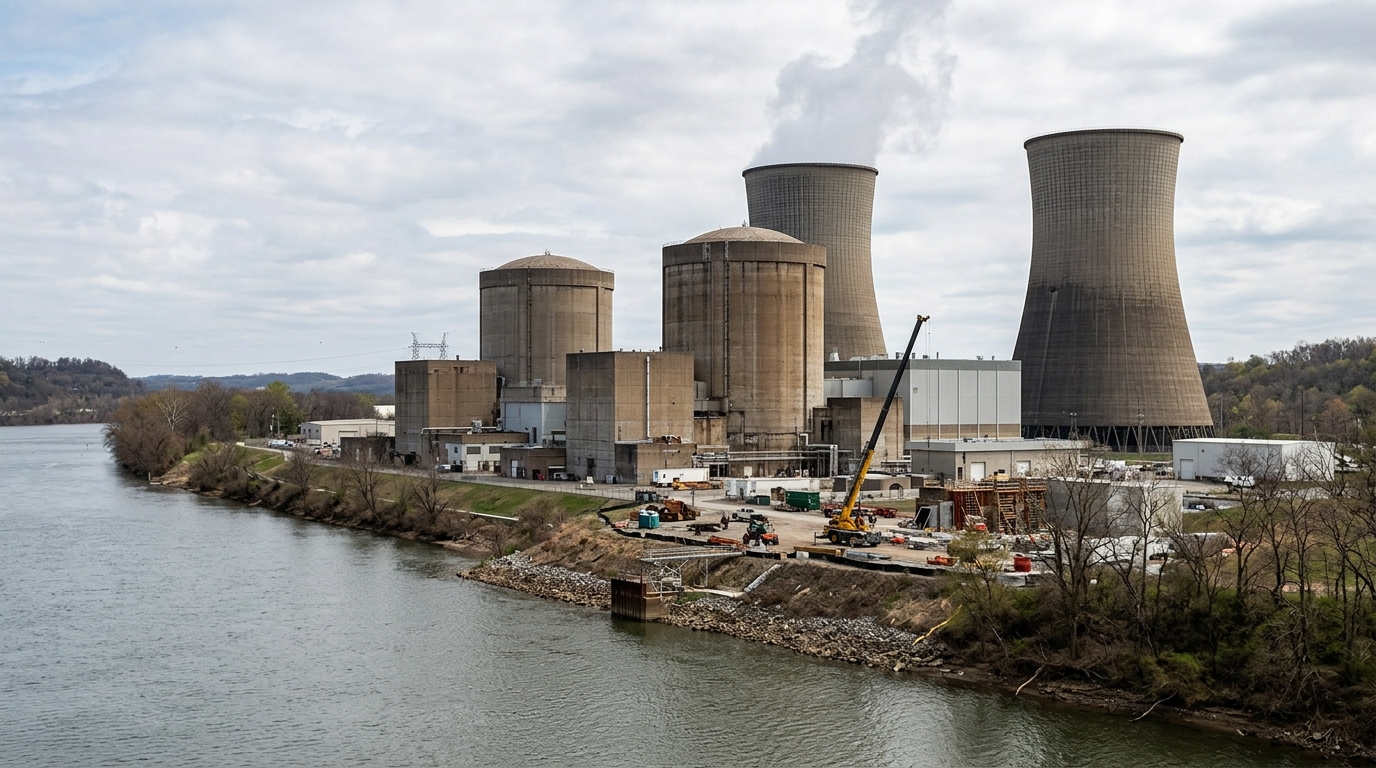
The debate over whether utilities have become AI plays just got a concrete dollar figure attached to it. The U.S. Department of Energy’s Office of Energy Dominance Financing announced Monday a conditional loan commitment of up to $4.2 billion to finance nuclear uprates and modernization across Vistra’s nuclear fleet in Pennsylvania and Ohio. Energy Secretary Chris Wright made the announcement at Vistra’s Perry Nuclear Power Plant along Lake Erie. Vistra shares climbed 3.5% on the day.
The operational mechanics are straightforward enough. Vistra’s planned investments at Beaver Valley in Pennsylvania and Davis-Besse and Perry in Ohio will produce more electricity from existing plants without requiring new transmission corridors, while supporting operation for an additional 20 years beyond existing licenses. The initiative will add 433 megawatts of new capacity on top of preserving nearly 4 gigawatts of existing baseload output. The harder question is what the loan does to the competitive landscape for everyone who did not receive one.
Why Institutional Investors Are Paying Attention
The loan does not simply lower Vistra’s cost of capital on a discrete project. It restructures the economics of the entire PJM nuclear trade. The DOE commitment could change how Vistra pays for the program. On earlier earnings calls, CFO Kris Moldovan had listed the Meta-backed PJM nuclear uprates among growth investments Vistra planned to fund from internally generated cash in 2026 and 2027. Subsidized federal credit frees that cash for other uses, or for additional uprates. Competitors funding identical projects off their own balance sheets carry a structurally higher cost base from the start.
Meanwhile, the regulatory backdrop for the broader PJM nuclear trade remains complicated. On September 29, 2026, FERC placed a five-month hold on PJM’s reliability backstop procurement submission, citing concerns over the fairness of the proposed cost allocation. The order accepts PJM’s proposal but suspends it until February 28, 2027, subject to refund and the outcome of additional proceedings. That delay pressured shares of CEG and TLN at the end of last week, and it makes the DOE loan to Vistra look even more significant. Federal credit partially insulates one operator from regulatory uncertainty that continues to weigh on its peers.
The Bull Case for Vistra
The bull argument is not complicated. Vistra has already demonstrated comfort with government loan structures, having secured a $583 million Texas Energy Fund loan in June 2026 at a fixed rate of 3.0% per annum for its 860-megawatt Permian Basin peaking project in west Texas. Layering $4.2 billion of similarly priced federal debt onto nuclear uprates that are already contracted to Meta at long-term rates produces visible, durable free cash flow at a cost no private lender can match. Vistra has signed power purchase agreements with Meta covering its PJM nuclear facilities, with agreements also supporting subsequent license renewal for an additional 20 years across the four nuclear units involved.
What Bears and Peers Are Missing
The bear case on Vistra focuses on execution and conditionality. The DOE itself noted that while the conditional commitment indicates intent to provide a loan, Vistra must still satisfy certain technical, legal, environmental, and financial conditions before the department enters into definitive financing documents and funds the loan. Slippage on any of those conditions delays a project whose uprate capacity deliveries are not expected until the early 2030s.
But the more interesting debate belongs to investors holding Constellation and Talen. CEG and TLN both fell after FERC’s September 29 decision, with both companies owning substantial power-generation assets exposed to the PJM market where changes to capacity prices and new-generation procurement directly affect earnings. Talen is particularly sensitive because the value of its concentrated merchant nuclear exposure depends heavily on the price, duration, and risk allocation achievable in long-term customer contracts. Neither company has announced a DOE loan of comparable scale for its uprate program. That gap in financing cost is not yet reflected in how most analysts model the spread between these names.
Stocks to Watch
Vistra (VST) is the clearest beneficiary. The loan converts a balance-sheet-funded growth program into federally subsidized infrastructure with contracted revenue behind it. The 3.5% move on Monday likely understates the long-run valuation impact if the commitment reaches financial close.
Constellation Energy (CEG) received a separate $1 billion DOE loan for its Crane Clean Energy Center in November 2025, which marked the first time the DOE Loan Programs Office concurrently finalized a conditional loan commitment and financial close. But potential data center customers are waiting to see how PJM’s pending rules for colocating load and the reliability backstop process shake out, which caps near-term catalysts regardless of balance sheet strength.
Talen Energy (TLN) carries the most merchant exposure and the least federal credit support among the three. Talen cleared 10,180 megawatts in the 2028/2029 PJM capacity auction, equating to approximately $1.208 billion in capacity revenues for that planning year, which is a genuine tailwind, but a widening financing-cost gap versus Vistra is a risk that deserves more analyst attention than it is currently getting.