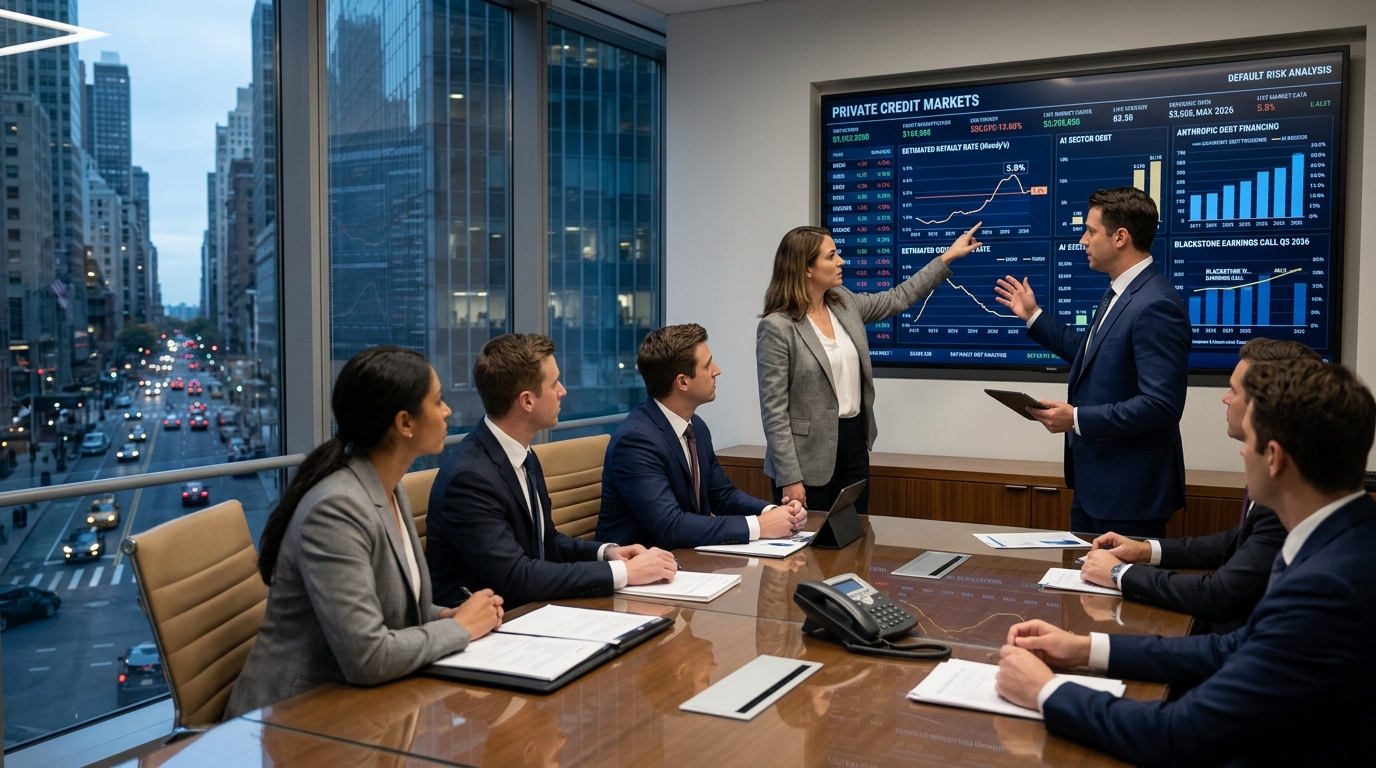
The investment committee question heading into Thursday is deceptively simple: does Blackstone’s private credit business look as safe as advertised? Moody’s warning this year about how extensions and PIK can mask stress, and the turbulence in AI debt markets this week, mean the answer is no longer obvious.
Blackstone is expected to post quarterly earnings of $1.31 per share when it reports Q3 2026 results before the open on October 22, on revenues of $3.36 billion. The firm has beaten the consensus estimate in each of the trailing four quarters, with an average beat of nearly 14%. So the number itself may prove fine. What professional investors are interrogating is the environment around it.
The Default Math Problem
Borrowers in the U.S. private debt market are using delayed interest payments and maturity extensions to avoid default, potentially masking the overall extent of credit stress, according to Moody’s Ratings. The headline finding: Moody’s evaluated 607 credit estimate issuers over the 12 months to June 2026 and found 4.0% were reported as defaults. When payment-in-kind amendments and maturity extensions among distressed issuers were included, that rate rose to 5.8%.
That 180-basis-point gap is the argument that the private credit industry has been papering over stress rather than resolving it. For Blackstone specifically, the implication cuts both ways. Consistent negative headlines surrounding private credit have adversely impacted flows across the non-traded BDC market, including BCRED. Yet BCRED’s own loan book has so far held up: interest coverage ratios in the portfolio were 45% higher in Q2 2026 compared to Q1 2024. The bull case is that Blackstone’s scale and underwriting discipline leave it in a different risk bracket than the middle-market stress Moody’s identified. The bear case is that PIK amendments are, by construction, invisible until they stop working.
The Anthropic Wager
Into that debate steps Project North Star. Anthropic is offering Blackstone a double-digit return on debt financing for a $60 billion AI chip deal, the Financial Times first reported. The financing package would support Anthropic’s acquisition of approximately 1.5 gigawatts of Google’s custom tensor processing units.
Blackstone-managed funds are expected to invest $9 billion in junior debt backed by Anthropic’s five-year chip lease payments, representing half of the planned $18 billion junior financing. The firm has been offered a 10% coupon, with total returns exceeding that level after accounting for issuance discounts and fees. By comparison, similarly rated borrowers typically pay yields of approximately 7% in public bond markets. Anthropic sold about $4.4 billion of similar debt only four months ago at an 8.5% interest rate. Rates are moving in the wrong direction, and fast.
Blackstone is not the only private credit anchor being pulled into AI chip financing at yields that would have seemed implausible a year ago. Broadcom is arranging a separate $50 billion private financing round for its OpenAI chip program, with Apollo and Blackstone again among the lenders in discussions.
The timing is awkward. Yields on CoreWeave’s junk bonds moved above 15% this week, a level usually signaling distress. Separately, public-market appetite for AI data center and compute-linked paper has clearly weakened, even if deal flow can swing month to month. The public market is actively pushing yields higher on AI infrastructure credit while Blackstone is being asked to anchor the largest such deal ever done.
What Investors Are Missing
The conversation about Thursday’s results will focus almost entirely on distributable earnings and AUM growth. The consensus estimate for total AUM of $1.38 trillion implies growth of 11.1% from the prior-year quarter. That figure will look reassuring in a headline.
What deserves harder scrutiny is the pricing signal embedded in the Anthropic offer. The latest terms indicate investors are demanding higher risk premiums to finance the rapid AI build-out, while technology groups are accepting steeper costs to secure large commitments and anchor backers. Blackstone’s internal rationale for accepting a 10%-plus coupon on junior chip debt, at a moment when the public junk market is stepping back from similar collateral, is the conversation Thursday’s earnings call should force into the open. Management’s language around AI credit underwriting will matter as much as the distributable earnings line.
Stocks to Watch
- Blackstone (BX): The earnings call is the event. Watch for any commentary on AI compute lending strategy and whether BCRED inflows stabilized after Q1’s deceleration.
- BCRED: Blackstone’s flagship private credit fund posted its first monthly loss in more than three years in February, one of the clearest signs of weakening performance in the $1.8 trillion market. September’s reported 1.6% monthly return complicates the bear case, but the Moody’s default-rate methodology is a structural challenge to NAV credibility across the BDC universe.
- Ares Capital (ARCC): As the largest publicly traded BDC, it carries the same PIK and maturity-extension exposure Moody’s flagged. Any re-rating of how the market prices private credit default risk lands on ARCC first.
- CoreWeave: The canary. Bond prices tied to U.S. AI data center projects have fallen as investors question whether future revenue can support heavy borrowing, with CoreWeave-linked debt trading at distressed levels and yields moving above 15%. Where CoreWeave’s bonds trade on Thursday morning sets the mood for how the market receives Blackstone’s Anthropic commitment.