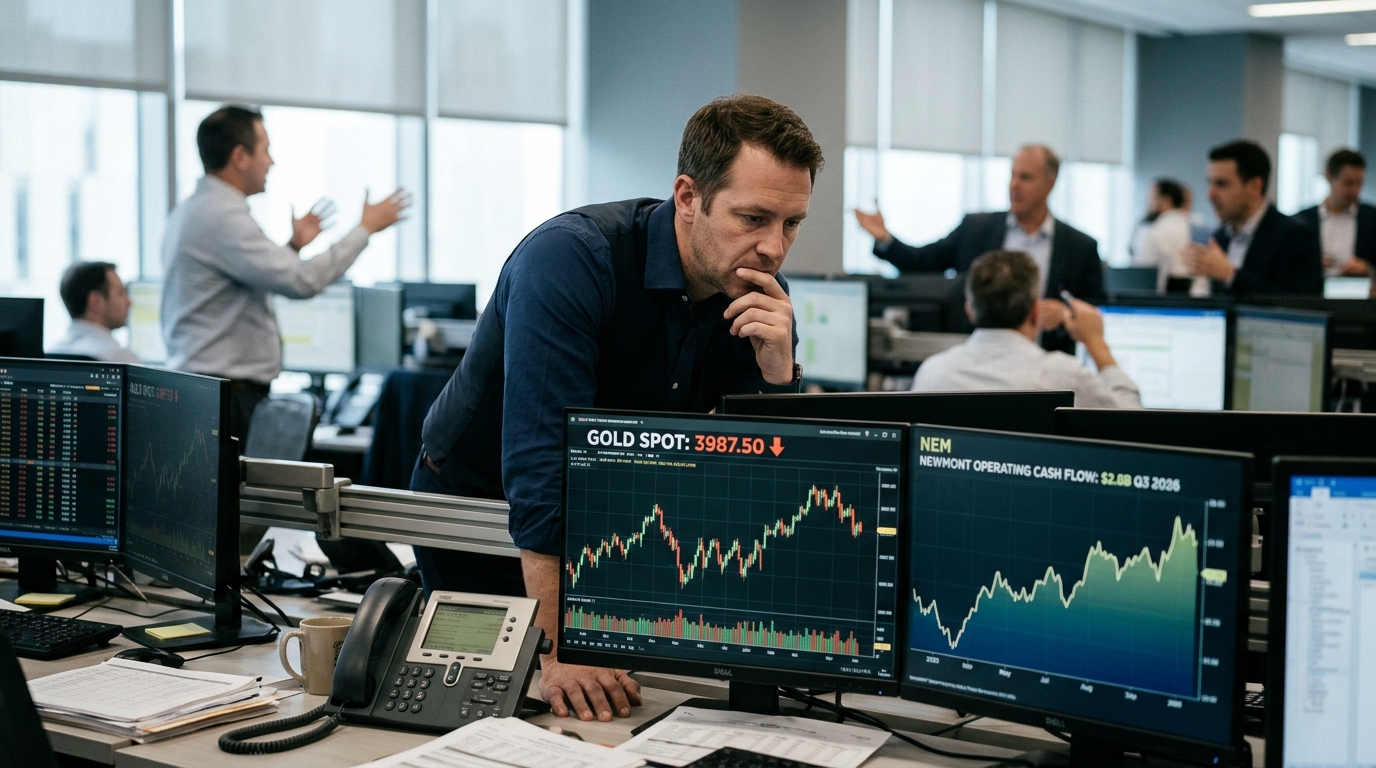
The debate inside every commodities desk this morning is not whether gold is broken. It is whether the drop below $4,000 is the kind of forced selling that actually creates opportunity in the miners, or a signal that the three-year bull cycle has rolled over for good.
Here is what we know. Spot gold dipped below $4,000 in Asian trade on Friday, October 23, 2026, touching roughly $3,987 and marking the lowest levels since mid-July, after an AI-led stock rout pushed investors to sell across assets. Bullion had already fallen about 2.8% on Thursday. Brent crude traded as high as $114 a barrel Friday, reinforcing inflation and rate concerns, and futures pricing has kept December hike odds elevated.
Hours before the selloff deepened, Newmont delivered numbers that reframe the entire conversation. The company posted Q3 adjusted net income of $2.20 per diluted share, with AISC of $1,454 per ounce and improved full-year cost guidance to $1,520 per ounce. The average realised gold price of $4,317 per ounce helped lift margins, with cash from operations totalling $2.8 billion and the balance sheet holding $8.8 billion in cash. Free cash flow reached $1.9 billion in Q3.
That $2,863 per ounce spread between Newmont’s AISC and its Q3 realised price is the number institutional investors should be sitting with. Even if gold settles at $3,900, Newmont is still generating margins that most industrial companies never see.
The Bull Case
The bulls argue this selloff is structural noise dressed up as trend. The selling is cross-asset and collateral-driven, not a regime change. And the miners, on current numbers, have never been better positioned to absorb a correction. Management indicated Newmont is transitioning beyond a 2026 production trough, with low to mid single-digit percentage production growth expected to begin in 2027. Production growth into expanding margins is exactly the setup generalist funds historically re-rate.
The same dynamic is playing out across the broader mining sector. BHP’s copper output fell 19% in the same quarter that cash copper hit a record, leaving investors to weigh production shortfalls against record commodity prices.
The Bear Case
The bears read it differently. With oil near $114 and the market still treating a December Fed hike as plausible, the risk is that real yields keep rising and gold’s floor moves lower than $3,900. NEM stock closed the regular session Thursday, October 22, 2026 at $114.11, down 2.62%, and then traded higher after-hours following the earnings release, suggesting the market is not yet willing to value the company on its earnings power alone.
What Investors Are Missing
The overlooked implication: Newmont’s realised price for Q3 was $4,317 per ounce. Spot is now about $330 below that. The company locked in margins that no longer exist on paper, yet those cash flows already sit on the balance sheet. Since the last earnings call, Newmont said it returned about $1.9 billion to shareholders through dividends and buybacks, including $1.6 billion of share repurchases, and has reduced its share count by over 115 million shares, roughly 10% of shares outstanding, since February 2024. A company buying back 10% of itself while generating record cash on a metal that is falling is a different business than the one most models price. The street keeps marking NEM off the spot fix. The income statement says that is the wrong frame.
Stocks to Watch
- Newmont (NEM): Citigroup raised its price target to $140 on October 20, 2026.
- VanEck Gold Miners ETF (GDX): GDX closed at $81.69 on October 22, 2026, and was down about 4.8% year-to-date at that point, even as its underlying constituents are posting record cash generation. That divergence between earnings and price is where institutional interest concentrates.
- Physical gold (XAU/GLD): The Federal Reserve’s next policy meeting is scheduled for October 27 to 28, 2026, with the decision due October 28. The outcome either validates the liquidity-selling thesis or confirms a new rate ceiling that grinds spot lower. Either way, it sets the price from which miners will be valued into year-end.