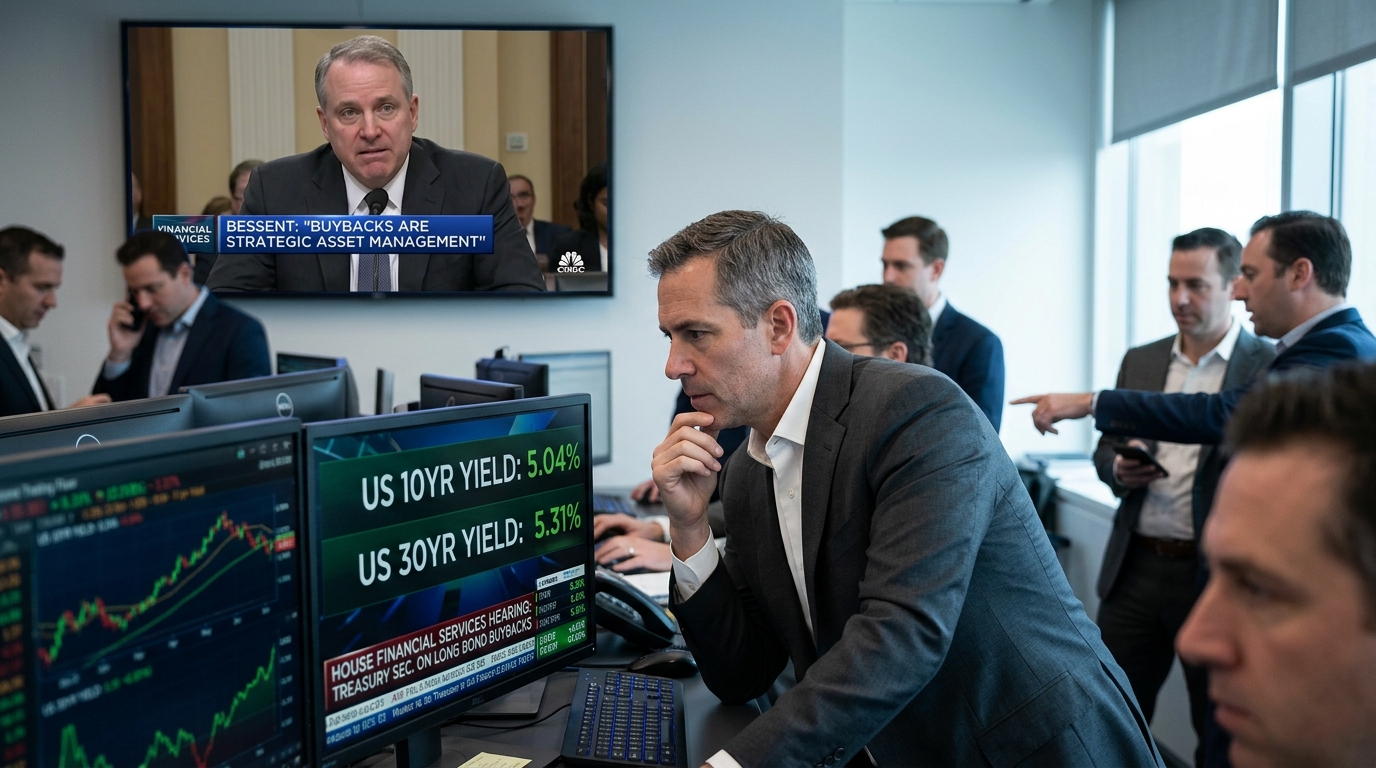
Tuesday produced something institutional bond desks rarely have to price: the U.S. Treasury Secretary, under oath before Congress, defending an expanded program of long-dated Treasury buybacks even as the 10-year yield touched 5.041%, its highest level since July 2007.
The House Financial Services hearing was formally scheduled as annual testimony on the state of the international financial system, but it quickly became a referendum on Treasury’s bond market management. Bessent defended the department’s long-end buybacks as liquidity support even as members pressed him on why yields have continued to rise. Bessent pushed back, arguing that yields would be even higher without Treasury’s intervention.
A Coordination Problem the Buy Side Cannot Ignore
The political optics are one thing. The market structure question is another, and it is the one that matters more to portfolio managers. Treasury Secretary Bessent is in the midst of an unusually visible effort to lean against higher long-term yields, and it may also be complicating the work of his counterpart at the Federal Reserve, Chairman Kevin Warsh. The two institutions are pulling in opposite directions: Treasury buying the long end while the Fed is widely expected to raise the short end on Wednesday for the first time since 2023.
The Federal Reserve is expected to lift interest rates on Wednesday for the first time since 2023, a move that has already put Warsh at odds with President Trump, who has publicly called for lower rates. Markets have priced in a strong likelihood of a quarter-point hike in Wednesday’s vote, which would widen the very spread Bessent is trying to compress.
The Buyback That Backfired
The mechanics of Treasury’s intervention have not inspired confidence. The Treasury Department purchased $5.19 billion of debt maturing in 10 to 20 years on September 10, falling short of the $6 billion maximum it had announced, and benchmark 10-year yields extended their rise after the operation, reaching 4.95%, their highest since 2023.
The forces pushing yields higher are, by most accounts, structural rather than technical: federal debt has passed $40 trillion, inflation expectations have been revived by tariffs and the Iran war’s effect on energy prices, and heavy corporate borrowing to fund the AI buildout is competing for the same investor capital. Against that backdrop, even an expanded buyback program has limited reach.
Economists across the political spectrum argue the real issue is the federal deficit itself, not a market malfunction the Treasury can fix with buybacks. Unlike the Federal Reserve, which can create money to calm markets in a crisis, the Treasury has no such power, leaving Bessent trying to manage a problem with tools critics say were never built for the job.
What Investors Are Missing
The debate has focused almost entirely on whether buybacks can move yields. The more consequential question is what Bessent’s public defense of the program does to price discovery. When the issuer of debt frames its own bonds as dislocated, it removes ambiguity about intent, but it also signals structural concern. Markets that were already demanding a higher term premium now have explicit confirmation that the government is uneasy about where the long end is clearing.
Mortgage rates have moved back above 7% in recent days, as rising oil prices, hot inflation readings, and fiscal concerns deepened the bond market selloff. That transmission from the long end of the Treasury curve into household borrowing costs is where the political and market story converge, and where the cost of failing to move yields becomes concrete.
Stocks to Watch
TLT (iShares 20+ Year Treasury Bond ETF). The most direct expression of the debate. If the Fed delivers its hike and then pivots to more data-dependent language, long-end yields could stabilize after the decision and TLT could benefit. The key risk is the Fed signaling more hikes, which would push long-term yields higher and hit TLT further.
US 30-Year Treasury. The 30-year yield rose to roughly 5.34% after the September 10 buyback operation, near the highest levels seen since the mid-2000s. Any confirmation from Warsh that the September hike is one-and-done could provide relief here. Any hint of additional tightening accelerates the selloff.
Goldman Sachs (GS) and Morgan Stanley (MS). Higher long rates conventionally support bank net interest income, yet a rate spike large enough to trigger risk-off can outweigh the margin benefit in a single session. Both firms are exposed to the same tension: structurally supportive rate backdrop, tactically hostile when duration assets reset violently. Watch how their fixed income trading revenues respond to the sustained volatility in the weeks ahead.