The investment committee question on China consumer stocks used to be about timing. Today’s data makes it about something harder: whether there is a structural ceiling on spending that no stimulus package can lift.
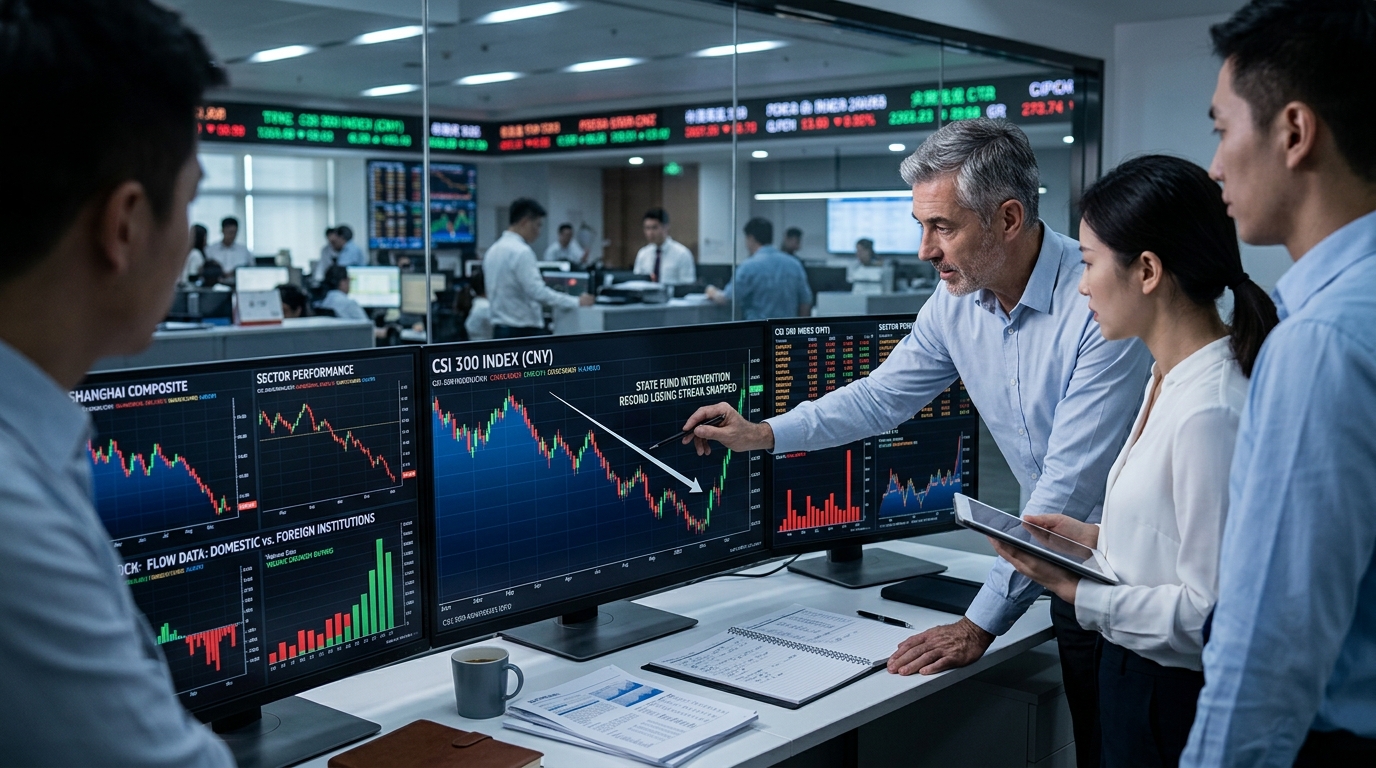
Retail sales rose 0.4% year on year in October, missing a 0.8% forecast and slowing from a six-month high of 1.1% in September. That would be a soft number in any month. October included a national holiday and the Singles Day shopping festival, making it the month China’s consumer is supposed to show up. It did not. Industrial output expanded 4.8% year on year, missing the 5.3% estimate and slowing from 5.5% in September. Fixed-asset investment fell 8.1% in January to October, worse than the expected 7.0% drop. Every line missed.
The Bull Case: Cyclical Weakness, Structural Patience
The optimistic read is that investors are discounting companies at cyclical-trough valuations when the cycle will eventually turn. PDD trades at a trailing P/E of about 8.9. That is a compressed multiple for a business generating the kind of margins most Western retailers cannot imagine. JD’s second-quarter net margin was 2.1%, while PDD’s was about 24.2%. Even in a weak consumer environment, PDD’s low-price positioning and rural reach can outperform because value-seeking is exactly what a pinched consumer does. The bull case adds that Shenzhen this week matters: news reports say Trump, Xi and Putin are expected to meet Thursday on the sidelines of APEC, after a trade truce was extended until January.
The Bear Case: Property Is Not a Cycle, It Is the Problem
The bear case is not about October. It is about five years.
Residential real estate is often estimated at roughly 70% of urban household assets, and prices have been falling since the downturn that began in 2021. China’s new-home sales fell about 13% by value in 2025. The wealth effect is operating in textbook fashion, but the unusually large weight of housing in household balance sheets makes the drag larger and more persistent than equivalent corrections in the United States or Europe.
The property drag on consumer spending has a direct read-through to China’s digital advertising market. Baidu’s online marketing revenue fell 19% as weak consumer spending caused businesses to cut advertising budgets, illustrating how the same household balance-sheet pressure flows upstream into platform revenue.
Household deposits have risen sharply over the past five years as consumers favor saving over spending, constraining the domestic demand recovery Beijing’s own targets depend upon. Singles Day, the clearest consumer stress test of the year, confirmed it. Syntun estimated cumulative sales through October 31 topped 1 trillion yuan, roughly matching the level of 12 months before. Flat in a holiday month, against a record from 2025, is not a cyclical dip. Strong exports have reduced the urgency of introducing policies to stimulate spending at home, analysts said, which means the relief valve that might correct this is not under pressure to open.
The price environment complicates the picture further. A widening gap between China’s producer and consumer prices is squeezing manufacturers even as household spending stays flat.
What Investors Are Missing
The debate frames this as cyclical versus structural as if the two are mutually exclusive. They are not, and that distinction matters for how to position.
PDD and Alibaba are not pure consumer plays anymore. Alibaba’s core commerce revenue depends heavily on domestic consumer spending, so weak demand can pressure advertising and retail transaction growth, but Alibaba is simultaneously running a large cloud and AI infrastructure business that does not require a confident Chinese household. PDD’s international Temu business operates entirely outside China’s property-deflation channel. The overlooked question is not whether the Chinese consumer recovers. It is whether these platforms have enough non-consumer revenue to generate returns while the consumer stays depressed for another two years.
The Shenzhen meeting changes the tariff risk calculus, not the consumption problem. One widely circulated view is that the headline issue will be whether the two leaders agree to extend the trade truce past its January deadline, and that a follow-up at the G20 in December could reduce the pressure to settle everything at APEC. That means investors buying China consumer names as a Shenzhen trade may be solving for the wrong variable.
Stocks to Watch
- JD.com (JD): Reports Q3 results Tuesday, November 17, 2026, before market open. Last quarter, JD beat the consensus EPS estimate of $0.86 by $0.07, delivering $0.93. Today’s data is the worst possible preview. JD’s first-party retail model and thin margins leave it most exposed to a consumer who is simply not upgrading purchases.
- PDD Holdings (PDD): Reports Thursday, November 19, 2026. Analysts expect earnings of $2.77 per share on revenue of about $17.2 billion. Value positioning is a relative advantage in a 0.4% retail environment, but Temu’s exposure to European duty changes complicates the offshore growth story.
- Alibaba (BABA): Persistent concerns over slowing growth, heavy spending on AI infrastructure, and intense competition in China’s e-commerce and instant-delivery markets have weighed on investor sentiment. Its AI cloud segment is the clearest way to own China technology without a full bet on consumer recovery.
- BHP (BHP): Steel, copper, cement, and glass all face sustained headwinds from Chinese property weakness. Fixed-asset investment falling 8.1% is a direct line to BHP’s earnings. This is the clearest short-side implication of today’s data for investors who do not want direct China equity exposure.