September 15, 2026
Bonus Content: BrightSpring’s Balance Sheet Is Now the Story
Gold and copper prices are rising fast. That’s a fact that’s impossible to ignore.
What many people are missing is that the opportunity to gain early exposure to companies exploring for these metals in Tier-1 jurisdictions may not last forever.
That’s where one little-known Canadian explorer comes into play. It has a small market cap and low share price alongside a strong treasury and major-company-funded drilling underway now in two premier Australian mineral belts.
Successful drilling could bring greater market attention to the copper-gold potential the company is targeting across its portfolio.
Access our brand-new FREE report to get the full story.
Inside, you’ll learn the company’s name and ticker symbol, explore its Australian project portfolio, and get the latest on drilling now underway.
Access the report by clicking here and learn just why this overlooked copper-gold explorer is well-positioned for significant upside.
BrightSpring’s Balance Sheet Is Now the Story
Wall Street spent much of 2024 arguing about whether BrightSpring could grow. That debate is largely settled. The one worth having now is what the company does with a balance sheet that has quietly become one of the cleaner stories in healthcare services.
At the Jefferies Healthcare Services and Technology Conference on September 14, 2026, CEO Jon Rousseau described a business entering a more mature phase, still expecting strong cash generation and market-leading expansion across pharmacy, home health, and related care lines. The framing matters. BrightSpring is no longer pitching a turnaround. It is pitching capital discipline.
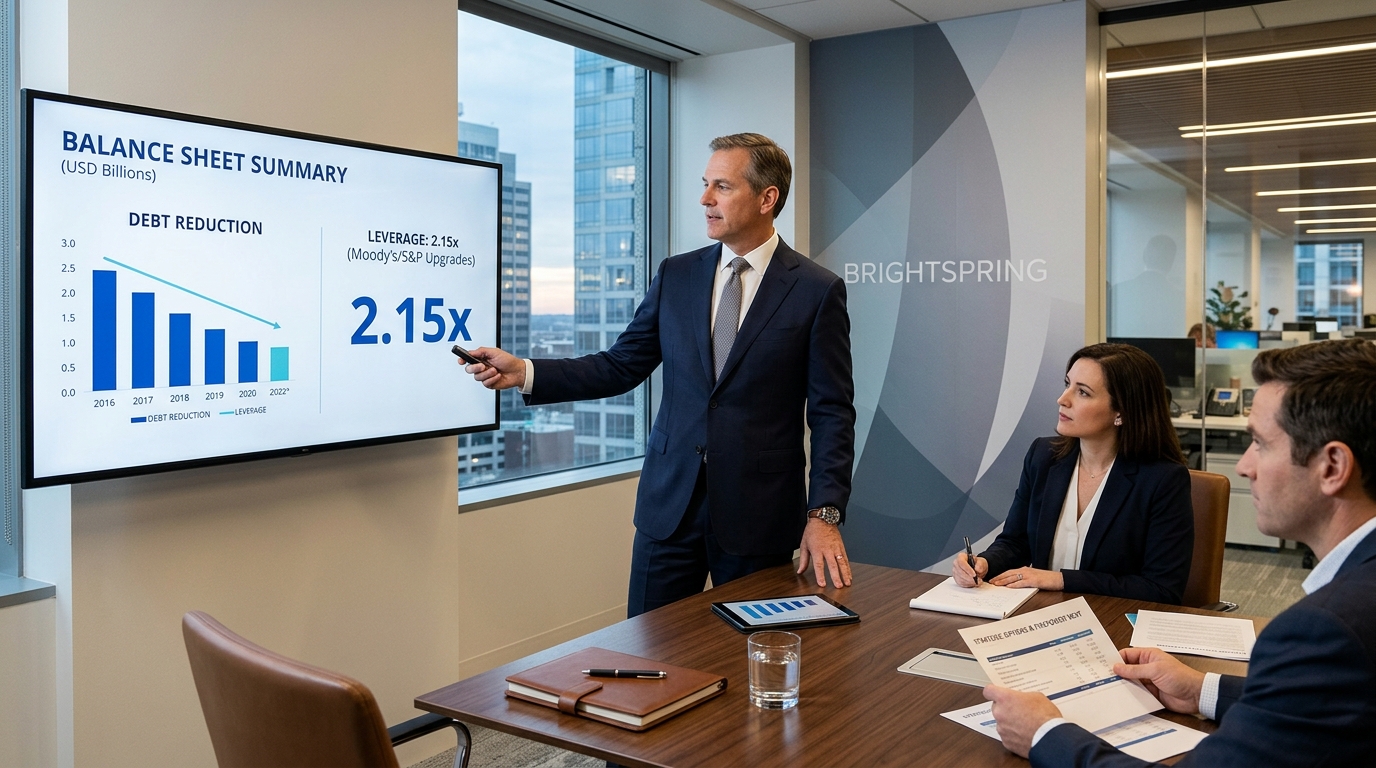
The numbers support that tone. Second quarter 2026 revenue came in at $3.873 billion, up 23% year over year, while adjusted EBITDA rose 44.2% to $206 million, and leverage fell to 2.15x after a $300 million term loan paydown. Both Moody’s and S&P upgraded BrightSpring’s credit ratings during the quarter, with Moody’s moving to Ba3 from B1 and S&P lifting the issuer credit rating to BB- from B+. That is two notches of recognition in a single quarter, not a rounding error.
The operational foundation underneath those figures is broader than most investors realize. Rousseau has described BrightSpring as a platform with six business segments: specialty pharmacy infusion, home and community pharmacy, home health, hospice, rehabilitation services, and an emerging primary care business. The company has also argued that it is the second-highest compound annual growth performer in healthcare services over multi-year periods, behind only Eli Lilly. That is a provocative benchmark, and it is one management keeps repeating in front of institutional audiences.
The IRA headwind is real and should not be dismissed. Management has cited expected 2026 revenue headwinds totaling nearly $775 million, split across specialty and infusion, brand-to-generic conversions, and home and community pharmacy. The company is absorbing that drag while still raising guidance, which is the operative fact. Full year 2026 revenue guidance now sits at $15.1 to $15.425 billion, implying 17 to 19.5% growth, with adjusted EBITDA guidance of $820 to $845 million.
What institutional investors are underweighting is the capital allocation optionality opening up. BrightSpring has pointed to more than $600 million of operating cash flow and about $500 million of free cash flow potential in 2026, and management has discussed room for acquisitions, buybacks, and possibly dividends, with leverage potentially falling below 2.0x by year-end absent new deals. The company is also deploying automation and AI tools across hiring, onboarding, intake, documentation, and patient care plans, a cost structure lever that is still early and rarely discussed at the sector level.
The valuation is not cheap. Over the last twelve months, revenue is up about 26%, and the stock trades around the low 20s on an EV/EBITDA basis. That multiple prices in continued execution. One missed quarter on the IRA absorption or a poorly structured acquisition changes the conversation fast. For now, BTSG is a company that has earned the right to be taken seriously as a capital allocator, not just a growth story. That is a different kind of pitch, and the market has not fully priced the distinction.